
The Asian session is usually quiet, but it still has small moves that repeat the same pattern: a raid, a turn and a pull-back to a gap. The Asian range scalp trades that pattern with small stops and small targets in the evening hours of New York time. This lesson gives the exact rules of our M6 model, a real filled win and a real filled loss from a year of gold, the whole year's numbers, the usual mistakes and a quiz.
The M6 rules, as our engine reads them
| Window | New York | UTC (winter) | PKT (winter) | IST (winter) |
|---|---|---|---|---|
| Asian scalp window | 20:00-23:30 | 01:00-04:30 | 06:00-09:30 | 06:30-10:00 |
| Index variant (NAS100, US500) | 20:45-22:15 | 01:45-03:15 | 06:45-08:15 | 07:15-08:45 |
In summer the UTC, PKT and IST times are one hour earlier. More in killzones and sessions.
- Bias. By default the daily bias is required, as in our other models. See the year's numbers below for what happens with and without it.
- A raid against the direction of any liquidity level in the window. See liquidity.
- A shift on the 5-minute chart, then a fair value gap within 4 candles of the shift. See market structure.
- The entry is the OTE. A limit order at 70.5% of the leg, and only when the gap overlaps the 62-79% zone, as in the OTE model.
- Stop and targets. The stop goes beyond the raid's extreme by twice the symbol's stop buffer. The targets are the next liquidity levels, nearest first. They are smaller than in our other models: the last one only needs to be 1.5R away, not 2R.
- Time limits. The order expires when the window ends; a trade still open is closed 1 hour after the window ends.
A real win: gold, 4 August 2026
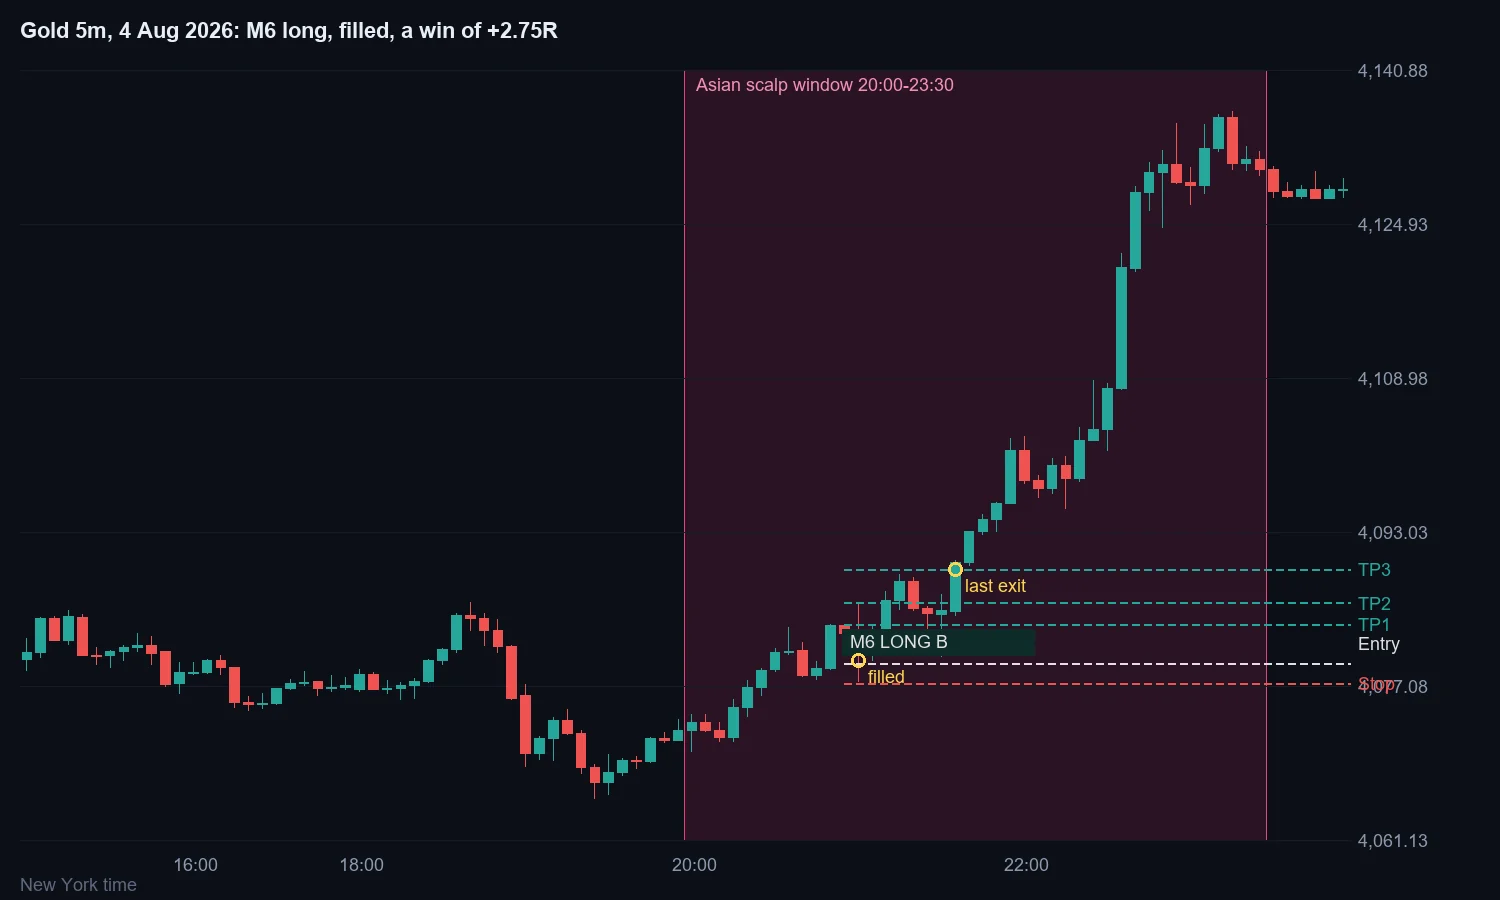
Gold took a 1-minute low early in the window and shifted up. The model bought at 4,079.45 with the stop at 4,077.37, a stop of just over two dollars. TP1 (4,083.45) and TP2 (4,085.72) were reached within two minutes of each other and TP3 (4,089.18) about half an hour later: +2.75R. Gold then kept rising for hours, which a scalp does not capture.
A real loss: gold, 20 August 2026
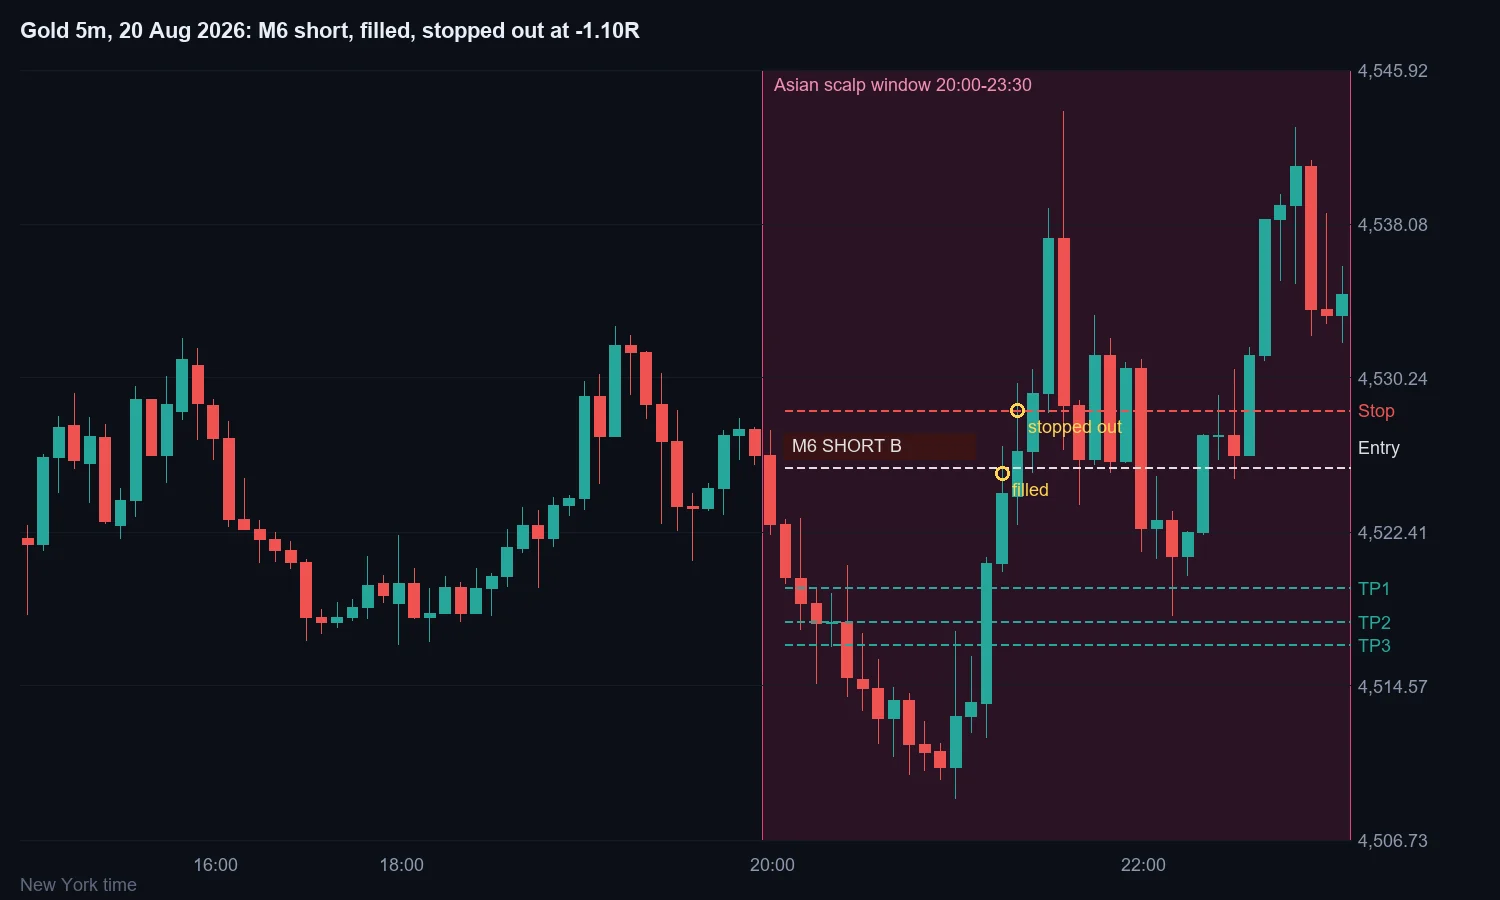
After a fall at the start of the window, the model sold the pull-back at 4,525.71 with the stop at 4,528.59. Price rallied through the stop within about fifteen minutes and the trade closed at a loss. The short was against the move that came next. Result: -1.10R.
The whole year on gold
Both trades come from one run of our strategy tester's simulator on gold 1-minute history, 1 October 2025 to 30 September 2026 (fills on the next candle, the stop checked first, the spread paid):
| M6 on gold, 1 Oct 2025 - 30 Sep 2026 | Setups | Filled trades | Win rate | Total | Profit factor |
|---|---|---|---|---|---|
| With the daily bias filter (the model's default) | 6 | 1 | 0 of 1 | -1.05R | - |
| Without the bias filter | 67 | 39 | 41% | +16.75R | 1.68 |
This is the first model in this course whose best number sits without the bias filter. With the bias filter M6 traded once in a year, so there is nothing to judge. Without it, 39 trades made +16.75R, with 41% winners and a worst run of 6.5R; seven months of twelve were positive and five were negative. Both trades above come from this unfiltered set, and without the filter the model takes whichever direction completes first. Be careful with the result: the three biggest winners (+6.73R, +4.31R and +3.83R) add up to 14.9R, so without them the year would have been about +1.9R. The simulator also uses one fixed spread for all hours, and spreads in the thin Asian hours can be wider, which matters for a scalp with a two-dollar stop. A good year on one market is a reason to test further, not a promise.
Test it yourself
Run M6 on your own market and months in the strategy tester in the web terminal (the free trial includes it), with the bias filter on and off. It uses the same rules and shows every trade, win or loss. If you try it live, start on a demo account.
Common mistakes
- Holding a scalp like a swing trade. The targets are small on purpose; take them.
- Ignoring the spread. With a stop of two or three dollars on gold, a wider spread eats a large part of every trade.
- Trading it every night. The model made only 39 trades in a year; many nights have no setup.
- Forgetting the clock change. In summer every UTC, PKT and IST time is one hour earlier.
- Trusting one good year. A few large winners made most of the result.
Check yourself: 3 questions
1. In New York time, when is the Asian scalp window, and what is different for NAS100?
20:00-23:30 New York time. For NAS100 and US500 the window is shorter, 20:45-22:15.
2. How do M6's targets differ from most of our other models?
They are smaller: the last target only has to be 1.5R from the entry instead of 2R, and an open trade is closed one hour after the window ends instead of two.
3. Why is the "without the bias filter" row more useful than the "with" row for M6?
With the filter M6 traded only once in the year, so that row says almost nothing. The unfiltered row has 39 trades, which is still a small sample, but enough to look at the pattern.
Practise it
Train your eye for the raid with the liquidity sweep practice in the Chart Challenge. For a related Asian-session model see the Asian Q2 Judas (M5).
Education only, not financial advice. Trading involves a high risk of loss; past results, including the tester numbers above, do not predict future results. Practise on a demo account first.
Open ICC Charts in your browser, free, with the ICT and VSA layers and the model scanner. Or practise on past charts in the free Chart Challenge game.
Open it on the chart → Play the chart gameNew articles and the daily chart challenge on Telegram → t.me/icccharts
More articles
- سلور بُلٹ کیا ہے؟ پاکستان کے وقت میں اردو گائیڈ
- پریمیم اور ڈسکاؤنٹ کیا ہے؟ ڈیلنگ رینج اردو میں
- رسک مینجمنٹ: ہر ٹریڈ میں کتنا رسک کریں؟ (اردو)
- مارکیٹ اسٹرکچر: BOS اور MSS کیا ہیں؟ (اردو)
- پرائس ایکشن کیا ہے؟ پرائس ایکشن اور SMC میں فرق (اردو)
- لیکویڈیٹی اور اسٹاپ ہنٹ کیا ہے؟ آسان اردو گائیڈ
- آرڈر بلاک کیا ہے؟ اردو میں (بریکر بلاک کے ساتھ)
- گولڈ میں لاٹ سائز اور ٹریڈنگ کا بہترین وقت (پاکستان ٹائم)
- فاریکس ٹریڈنگ کیا ہے؟ اردو میں بنیادی گائیڈ
- فیئر ویلیو گیپ (FVG) کیا ہے؟ آسان اردو گائیڈ
- اسمارٹ منی کانسیپٹ (SMC) اردو میں: آسان رہنمائی
- ICT کِل زونز پاکستان کے وقت میں (PKT)
- Price action क्या होता है? Price action vs SMC हिंदी में
- FVG (Fair Value Gap) क्या है? हिंदी गाइड
- ICT Killzones भारतीय समय (IST) में
- Order Block क्या है? हिंदी में (Breaker Block के साथ)
- CISD in ICT: change in state of delivery explained
- Breaker block entry rules: a step-by-step guide
- ICT Asian range and CBDR: marking them before London
- Market Maker Buy and Sell Model (MMXM) in plain words
- ICT PD arrays: how to rank zones in premium and discount
- How to backtest ICT concepts: journal 50 setups first
- Volume imbalance vs fair value gap: how to tell them apart
- Previous day and week highs and lows as liquidity targets
- Balanced Price Range (BPR): when two opposite gaps overlap
- Mitigation block vs order block: what is the difference?
- Equal highs and equal lows (EQH / EQL): obvious liquidity pools
- Inversion Fair Value Gap (IFVG): when a gap flips its role
- Displacement in ICT: what a strong move tells you
- London Close Reversal and London Protraction explained
- BOS vs CHoCH: break of structure vs change of character
- Inducement in trading: what it is and how to spot it
- Supply and demand zones vs order blocks
- Price action vs smart money concepts (SMC)
- Free MT5 FVG and order block indicator (same rules as ICC Charts)
- Chart Challenge: a free game to practise ICT concepts on real charts
- ICT daily bias: how to read the day's direction before the open
- Draw on liquidity: how to find where price is likely heading
- SMT divergence: how correlated markets can warn you before a reversal
- NWOG and NDOG: how ICT traders use opening gaps
- Power of 3 (AMD): accumulation, manipulation and distribution, with a real M8 setup
- Optimal Trade Entry (OTE, M4): the rules, a real win, a real loss and a year of results
- Premium, discount and the OTE: where to buy and sell in a range, with real chart examples
- ICT 2022 Mentorship model (M2): the rules, a real win, a real loss and a year of results
- Asian Q2 Judas (M5): the rules, a real win, a real loss and a year of results
- The ICT Unicorn model: when a breaker block meets a fair value gap
- Order blocks, breakers and mitigation blocks, with real chart examples
- ICT Silver Bullet: the M1 rules, a real win, a real loss and a year of results
- The Judas swing and turtle soup (M3): rules, a real win, a real loss and a year of results
- Wyckoff and VSA: reading accumulation and distribution with volume
- Fair Value Gap (FVG): meaning, real chart examples and how to trade it
- Liquidity in trading: buy-side, sell-side, sweeps and runs, with real chart examples
- Market structure: break of structure (BOS) vs market structure shift (MSS), with real chart examples
- Volume Spread Analysis (VSA) basics: effort, result and no supply
- ICT killzones and sessions: the times in New York, UTC, Pakistan and India, with real chart examples
- How to use the ICC Charts model scanner and alerts